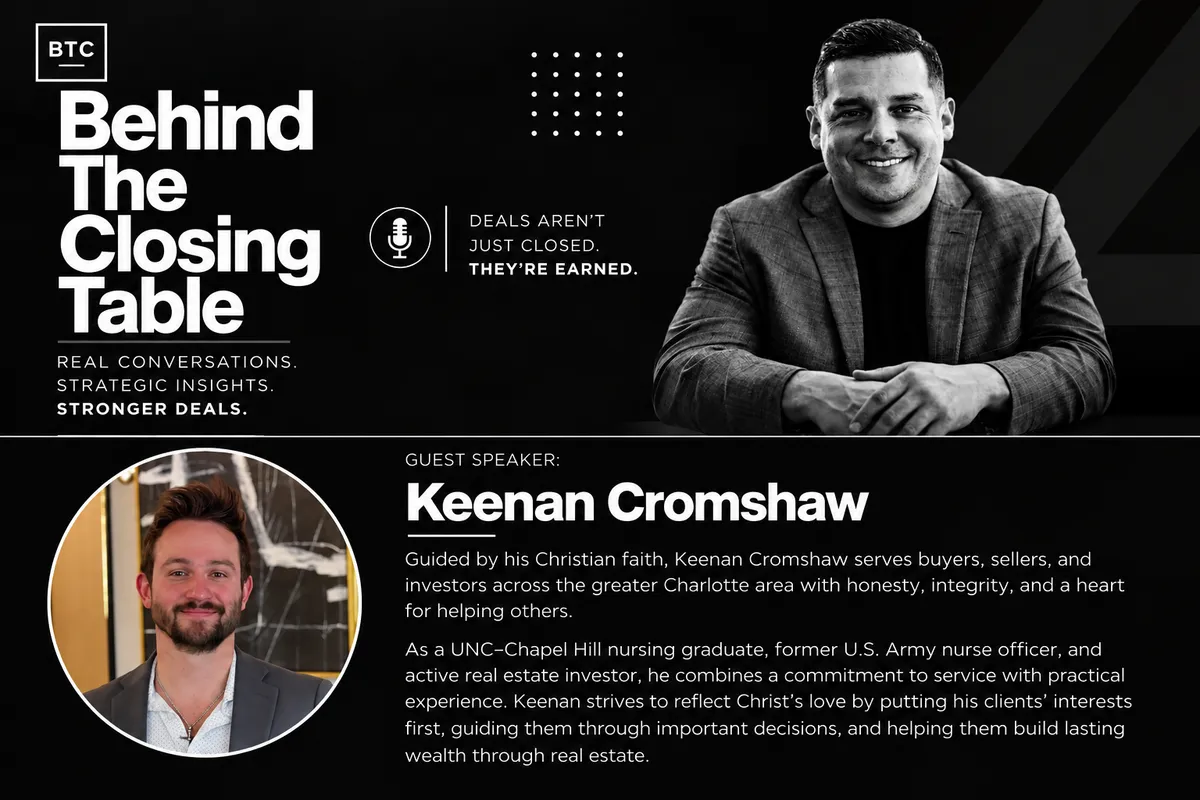
Behind the Closing Table: Matt Brady Talks Flipping Investing and VA Loans With Army Nurse Keenan Cromshaw
The Resume That Makes Keenan Cromshaw a Different Kind of Real Estate Agent
Matt Brady, the Carolina Mortgage Coach, welcomed Keenan Cromshaw of EXP Realty to Behind the Closing Table for one of the most practically useful conversations the show has produced. Keenan came to real estate through a path that included a nursing degree from UNC, a commissioned Army officer role serving at bases in Texas and Washington State, a house flip funded by a VA loan, additional investment properties, Airbnb management, and eventually a full-time real estate career in the Charlotte market. Each of those experiences shows up in how he serves buyers and investors today.
How the First House Started Everything
Keenan’s entry into real estate investing started with his VA loan in Texas while he was still on active duty. A common misconception he addresses directly is that the VA loan is only for veterans who have separated from service. He used it while still in uniform. He bought the home with zero down, made cosmetic improvements including painted cabinets, updated countertops, and landscaping sweat equity, and sold it the following year at a significant profit. That live-in flip introduced him to the returns possible in real estate and started the chain of events that led to where he is now.
The first actual investment flip came in Washington State near JBLM. He bought a property for approximately two hundred thousand dollars, put around eighty thousand into the rehab, and learned that his first flip was really about gaining experience rather than maximizing profit. The roof was more damaged than expected. There were hidden issues behind walls. He spent an entire day on landscaping he never wants to do again. But he also learned what to look for, how to budget for contingencies, and why a trusted contractor relationship matters more than construction knowledge on day one.
His rule since that experience is to budget at least ten percent above whatever the contractor estimates the rehab will cost. Hidden problems are not the exception in flipping. They are the expectation. The only flip he has done where costs did not run over by at least that margin is one.
What TV Shows Get Wrong About Flipping
The buy it for this, put in this, sell it for that narrative that drives TikTok videos and HGTV programming leaves out almost everything that determines whether a flip actually works. Time commitment is consistently underestimated. Keenan was working full-time as a nurse while managing his early flips and the hours required to oversee a renovation while holding a demanding clinical job are more than most people anticipate going in. The spreadsheet math looks clean. The reality of managing contractors, unexpected discoveries, and a timeline that almost always extends is something else entirely.
Profit margin discipline is the other major element the content leaves out. In the Charlotte market rental income generally does not justify holding a flip as a long-term rental if it does not sell, which means the purchase price has to be conservative enough to produce a real margin even if the after-repair value comes in below projection. Most of Keenan’s projects move from acquisition to sold in under six months with a two to four month rehab window followed by approximately a month on market and a month to close.
How to Spot a Cheap Flip Before You Buy One
Keenan walks buyers through specific tells that a renovation was done on the cheap rather than done right. Gaps between LVP flooring planks are what he calls the flipper special. Uneven grout lines in showers signal corner-cutting. But the most important issues are the ones you cannot see. Polybutylene pipes in homes built between the seventies and nineties are a significant concern in the Charlotte area with active class action history. Electrical is another major focus after Keenan experienced a house fire caused by knob-and-tube wiring that had been improperly integrated into a new panel. He was out on the lake when the fire department called. The house was empty. The outcome could have been far worse.
His professional standard now is that the homes he flips are places where families live and he approaches the electrical and plumbing work accordingly. He wants buyers walking into a property he has renovated to have peace of mind not a hidden bill waiting to surface.
What Buyers Panic About That Does Not Worry Him
Mold and foundation issues cause immediate alarm in most buyers. Keenan’s experience walking dozens of properties as both investor and agent gives him a more calibrated read on both. Mold in a crawl space or fungus growth that shows up on an inspection is often relatively manageable depending on the type and scope of the issue. Foundation concerns also exist on a spectrum and the difference between a few uneven joists and significant slab cracking is something his eye can assess before expensive due diligence money goes in. He can sometimes identify enough about a property’s condition in the initial walkthrough to advise a client before they commit to inspection fees.
What concerns him that buyers tend to ignore are the major systems. Roof, electrical, plumbing, and HVAC viewed through the lens of the buyer’s expected ownership timeline. A functioning system that is at the end of its useful life is a different conversation than a functioning system that has years left. He wants clients to understand what is coming in the years they will own the property not just what is working on the day they close.
VA Loans: Misconceptions on Both Sides of the Transaction
Matt makes clear he is passionate about VA loan education and Keenan adds the firsthand veteran perspective. The misconceptions they address together cover both borrower confusion and listing agent hesitation.
On the borrower side the belief that VA loans are only for veterans who have separated is common but wrong as Keenan’s own experience demonstrates. The belief that VA loans require high credit scores is also inaccurate. VA guidelines focus significantly on residual income rather than a minimum credit score threshold and the program is designed to be accessible to people who earned it through service.
On the listing side the belief that VA appraisals come in lower than conventional appraisals is statistically not supported. VA appraisals are comparable to or better than conventional appraisals by the data. The VA also provides a process called Tidewater where an appraiser who is trending toward a low value must reach out before issuing the report to allow the lender to submit additional comparable sales. After the report there is a reconsideration of value process available. No other loan program provides this level of advocacy built into the appraisal process.
Matt adds that VA loans allow seller credits to be used to pay off consumer debt which can meaningfully improve a veteran buyer’s financial position in a transaction. Keenan adds a detail often overlooked even by veterans themselves: the VA loan can be used to purchase up to four units. Buy and occupy one unit and rent the others. He did exactly this with one of his primary residences and it is one of the most effective wealth-building moves available to eligible service members and veterans.
How Being a Nurse and Army Officer Made Him a Better Agent
Matt draws a parallel between his own decade as a firefighter and EMT and Keenan’s nursing and military background. Both careers require staying calm under pressure, communicating clearly with people in stressful situations, and projecting confidence that helps others feel steadier than the moment would otherwise allow.
Keenan describes negotiating with listing agents as sometimes resembling his experience navigating relationships with physicians as a nurse. Knowing when to be tactful and when to be firm. Understanding how to lead without forcing. Those skills transfer directly to guiding clients through the most expensive purchase of their lives and negotiating on their behalf with the opposite side of a transaction.
What Newer Agents Should Ask When Evaluating a Team
Keenan joined a team immediately after getting licensed because he knew the investor world and the agent world overlap but are not the same thing. His advice to newer agents evaluating teams focuses on one question they often forget to ask. What is the lead flow and what is the quality of those leads?
Most new agents start with a sphere of a few dozen contacts. Of those very few are actively looking to buy or sell at any given moment. A team that provides consistent quality leads creates the at-bats that turn classroom knowledge into real competence. Learning real estate does not happen through presentations. It happens through conversations and transactions.
The Charlotte Market and Where Opportunity Still Exists
Keenan has recently purchased additional properties in the Charlotte market and does not see the opportunity closing. Charlotte continues to show strong job growth relative to comparable markets and has maintained property values better than many Sun Belt metros that saw more dramatic swings. Not every area works for investors right now but correctly priced properties in the right locations are still moving quickly. For flippers that matters because velocity of sale is a core part of the profit equation.
For buyers in the broader Charlotte and Carolinas market Matt notes that North and South Carolina rank among the top three destinations for people relocating nationally. The consistent inflow of new residents creates sustained housing demand that supports investment activity even when the broader rate environment makes some deals harder to pencil.
How to Reach Keenan Cromshaw
Call or text 910-471-1799. Email [email protected]. Find him on Instagram and Facebook by searching Keenan Cromshaw. He works with buyers, sellers, and investor clients across the Charlotte market.
Matt Brady, the Carolina Mortgage Coach, is available for VA loan pre-approval, conventional financing, and investor financing conversations across the Carolinas. Reach out to Matt Brady directly for lending support on any transaction.
Sources
CharlotteRegionalRealtorsAssociation.com
NAR.realtor
VA.gov
MortgageNewsDaily.com
Investopedia.com
