Your Local Mortgage Lender
Located in South and North Carolina
Personalized Mortgage Experience
Matt Brady offers personalized service and loan options you'll love. We shop multiple lenders to find the best rate and product for you, getting you into your dream home faster.
With wholesale interest rates and cutting-edge technology, we make the mortgage process seamless. Trust the experts who focus solely on mortgages. Support your local community and experience elite client service.
Let us help you achieve your homeownership dreams!
The Home Loan Process
Mortgage Pre-Approval
Get pre-approved from one of our Loan Officers to see how much you can afford.
House Shopping
Work with a trusted Real Estate Agent to find a home you would like to move into.
Loan Application
Complete your home loan application to get the lending process started.
Don't take my word for it
Mortgage Programs
Experience the best mortgage experience located in Clover,South Carolina.
Home Loan Options
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Conventional Home Loans.
FHA Home Loans.
USDA Home Loans.
VA Home Loans.
Frequently Asked Questions
How often can I refinance my mortgage?
There is no limit to the number of times you can refinance. However, you must qualify every time you apply and there will be costs associated with closing the loan each time.
Can I buy a home if I do not have money for a down payment?
Yes! There are a number of bond programs that offer low or no down payment financing options.
How do I know which mortgage is right for me?
The key to choosing the right mortgage is to understand the range of options and features available to you, as well as your budget, circumstances, and goals. Our licensed mortgage professionals are here to help you navigate that process. The more you know, the more comfortable and confident you will be choosing the best option for you and your family.
How long will the loan process take?
The Truth in Lending Act (TILA) does not permit a lender to close a loan until at least seven (7) business days have passed from the date your application was received. A typical home loan takes 30 days, as a number of third-party services such as appraisals, title work, and credit are required in conjunction with the mortgage process. Once you familiarize your Loan Officer with the details of your specific loan scenario, they will be able to provide you with a more specific timeline.
Will I qualify for a home loan?
The only way to find out is to speak with a qualified mortgage professional. Our Loan Officers have helped numerous clients who didn’t know if they could qualify to become home owners. We take the time to understand your financial situation and long-term financial goals, and then match you with the loan program that best fits your needs. Your approval for a loan may also largely depend on the price of the home you are financing. Getting pre-qualified prior to beginning your home search can give you an idea of what you may be able to afford.
Why do people refinance their mortgages?
Homeowners typically refinance to save money, either by obtaining a lower interest rate or by reducing the term of their loan. Refinancing is also a way to convert an adjustable loan to a fixed loan or to consolidate debts.
How much money will I have to pay upfront to buy a home?
This question does not have a simple, one-size-fits-all answer. The exact amount will depend on the price of the home you buy as well the type of mortgage financing you choose. Depending on your loan program, your down payment could be as much as 20% of the home’s price or as little as 3%, while some loans require no down payment at all.
Can I get a mortgage after bankruptcy?
You may still qualify for a home loan even if you have experienced a bankruptcy. The best way to find out if you qualify is to talk with a Loan Officer to discuss your options. Be sure to bring all paperwork regarding your bankruptcy so your Loan Officer can find the program that best fits your situation.
Should I lock my interest rate now, or wait until we are closer to our closing?
Interest rates fluctuate all day, every day. If an interest rate is good, it may be in your best interest to lock now. If you wait, you run the risk of an increase in rates later. If you are concerned that rates may go down after you lock, contact your Loan Officer to discuss your options. Some programs allow you to lock for an extended period and choose to lower your rate should a better one become available.
Most Recent Blog Updates
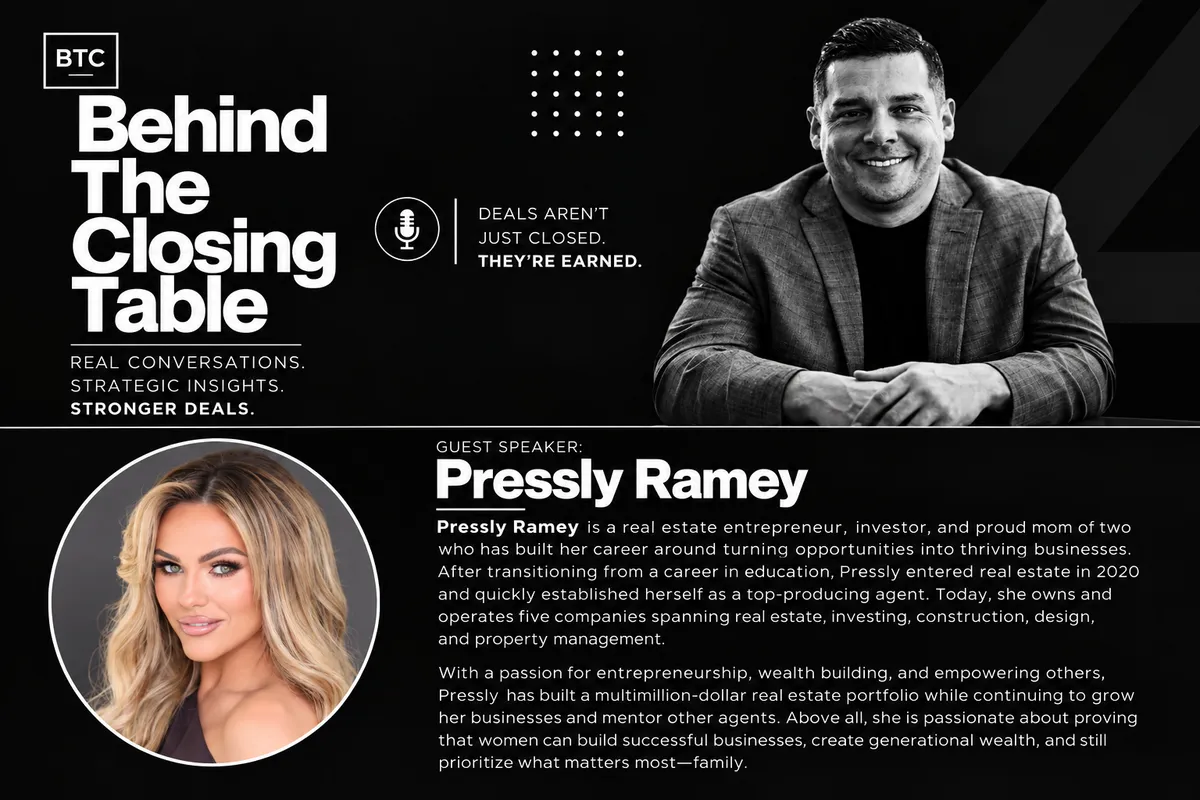
Behind the Closing Table: Matt Brady Talks Listings, Investing and Team Building With EXP’s Pressly Ramey
From Single Mom and Teacher to 74 Homes in Year One
Matt Brady, the Carolina Mortgage Coach, welcomed Pressly Ramey of EXP Realty to Behind the Closing Table for a candid conversation about launching a real estate career from scratch, pricing homes in today’s market, and why investing looks very different than it did a year ago.
Pressly had her first daughter at nineteen as a single mom in college and studied early childhood education, which led to five years teaching in public school. Her father is a tax and financial planner who invested in commercial, raw land, residential, and multifamily real estate, so she grew up watching the business. In 2020, while pregnant with her youngest daughter, she planned to take six months off from teaching and decided to get her real estate license, figuring even one flip a year could match a teacher’s salary. She finished her online course while up every night with a newborn, and sold 74 homes her first year with no team, no mentor, and no paid leads. She never returned to the classroom, but still gives back to teachers through Scholastic books and stuffed animal drives.
What Set Her Apart
Pressly credits fearlessness, hustle, and discipline. She says no room intimidates her, from a table with billionaires to a foreclosure auction, and that confidence, even when you are faking it until you make it, is how you survive. She grew her business entirely through sphere of influence and social media, has never paid for a real estate lead, and says social media produces roughly a million dollars a year in business for free. Another edge was a strong eye for design and for after repair value, which helped clients see immediate equity.
She has little faith in paid online lead generation, noting that agents often give up 50 to 70 percent of their split to portals. Her view is that your cell phone and consistent effort deliver the best return.
A Listing-Focused Team
Pressly intentionally moved to a listing-focused model so she could scale her other businesses, and her team now handles most buyer work. She leans on packages that bring her construction team in before listing: neutral paint, updated lighting, an accent wall, staging, deep cleaning, and landscaping, with the work floated to closing. She tells clients that once they hire her, it is her opinion of what sells, not theirs, and she is willing to carry the risk. She also cautions agents to be careful about liability and insurance when offering these services.
Her team is capped at a few agents, each with a defined role such as property management, broker in charge, or showings. She no longer puts her license on anything she has a financial interest in. Under the EXP organization she can bring agents in without the pressure of managing a large production team, and she wants them to build passive income and invest.
Pricing and the Current Market
Pressly says the data is out the window right now. She has personally invested in properties where the numbers show 50 to 70 thousand dollars of equity, and the market says otherwise. Her advice to sellers is to be transparent, patient, and realistic, since the market determines value. She is still seeing full price offers after 80 days on market, so a long time on market does not automatically mean a home is overpriced. New builders buying rates down to around 4 percent also compete with remodeled ranches. Matt adds that sellers who bought three to five years ago and did nothing to the house should not expect big appreciation, because the 20 percent annual jumps of the COVID era are gone.
Investing Right Now
Her first investment was a remodel in Bessemer City funded by private money at 12 percent interest, which also produced a free lot she used to partner with a builder. She says she would structure that deal very differently today, bringing the land to the table and splitting profits.
For beginners, she says the deals have never been better for those with capital, since people cannot sell. After five years of buying and selling 30 to 50 homes a year, she is currently finding success only with buy and hold. She is also using two-year leases with an option to purchase, giving tenants a portion of their rent toward equity, which tends to attract better tenants. Her biggest mistakes for new investors are being unprepared and overimproving a property for the neighborhood. Her father’s advice is to deduct 20 percent from your projected ARV and see if the deal still works. She also suggests looking beyond hot areas like Fort Mill and Charlotte, since outskirts such as Gaston County offer more margin and less risk, and always having three exit strategies.
Rapid Fire and Closing Thoughts
In a quick round, Pressly said the highest offer is not always the best, most realtors have a follow-up problem, you make your money when you buy, and a seller should consider a cash offer. Her advice to her nineteen-year-old self is simply to keep going. At the closing table she wants clients to feel peace, education, and no pressure.
Connect With Pressly Ramey
Pressly’s social links are in the comments of the video and blog. Reach out for buying, selling, or investment deals.
Matt Brady is the Carolina Mortgage Coach, helping buyers and investors across the Carolinas with financing. Reach out to Matt to talk through your next purchase.
Sources
CarolinaRealtors.com
NAR.realtor
Realtor.com
FreddieMac.com
ConsumerFinancialProtectionBureau.gov

Mortgage Calculator
See your total mortgage payments using the tool below.
| Year | Interest | Principal | Balance |
|---|

Social Media Links
YouTube
