Your Local Mortgage Lender
Located in South and North Carolina
Personalized Mortgage Experience
Matt Brady offers personalized service and loan options you'll love. We shop multiple lenders to find the best rate and product for you, getting you into your dream home faster.
With wholesale interest rates and cutting-edge technology, we make the mortgage process seamless. Trust the experts who focus solely on mortgages. Support your local community and experience elite client service.
Let us help you achieve your homeownership dreams!
The Home Loan Process
Mortgage Pre-Approval
Get pre-approved from one of our Loan Officers to see how much you can afford.
House Shopping
Work with a trusted Real Estate Agent to find a home you would like to move into.
Loan Application
Complete your home loan application to get the lending process started.
Don't take my word for it
Mortgage Programs
Experience the best mortgage experience located in Clover,South Carolina.
Home Loan Options
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Conventional Home Loans.
FHA Home Loans.
USDA Home Loans.
VA Home Loans.
Frequently Asked Questions
How often can I refinance my mortgage?
There is no limit to the number of times you can refinance. However, you must qualify every time you apply and there will be costs associated with closing the loan each time.
Can I buy a home if I do not have money for a down payment?
Yes! There are a number of bond programs that offer low or no down payment financing options.
How do I know which mortgage is right for me?
The key to choosing the right mortgage is to understand the range of options and features available to you, as well as your budget, circumstances, and goals. Our licensed mortgage professionals are here to help you navigate that process. The more you know, the more comfortable and confident you will be choosing the best option for you and your family.
How long will the loan process take?
The Truth in Lending Act (TILA) does not permit a lender to close a loan until at least seven (7) business days have passed from the date your application was received. A typical home loan takes 30 days, as a number of third-party services such as appraisals, title work, and credit are required in conjunction with the mortgage process. Once you familiarize your Loan Officer with the details of your specific loan scenario, they will be able to provide you with a more specific timeline.
Will I qualify for a home loan?
The only way to find out is to speak with a qualified mortgage professional. Our Loan Officers have helped numerous clients who didn’t know if they could qualify to become home owners. We take the time to understand your financial situation and long-term financial goals, and then match you with the loan program that best fits your needs. Your approval for a loan may also largely depend on the price of the home you are financing. Getting pre-qualified prior to beginning your home search can give you an idea of what you may be able to afford.
Why do people refinance their mortgages?
Homeowners typically refinance to save money, either by obtaining a lower interest rate or by reducing the term of their loan. Refinancing is also a way to convert an adjustable loan to a fixed loan or to consolidate debts.
How much money will I have to pay upfront to buy a home?
This question does not have a simple, one-size-fits-all answer. The exact amount will depend on the price of the home you buy as well the type of mortgage financing you choose. Depending on your loan program, your down payment could be as much as 20% of the home’s price or as little as 3%, while some loans require no down payment at all.
Can I get a mortgage after bankruptcy?
You may still qualify for a home loan even if you have experienced a bankruptcy. The best way to find out if you qualify is to talk with a Loan Officer to discuss your options. Be sure to bring all paperwork regarding your bankruptcy so your Loan Officer can find the program that best fits your situation.
Should I lock my interest rate now, or wait until we are closer to our closing?
Interest rates fluctuate all day, every day. If an interest rate is good, it may be in your best interest to lock now. If you wait, you run the risk of an increase in rates later. If you are concerned that rates may go down after you lock, contact your Loan Officer to discuss your options. Some programs allow you to lock for an extended period and choose to lower your rate should a better one become available.
Most Recent Blog Updates
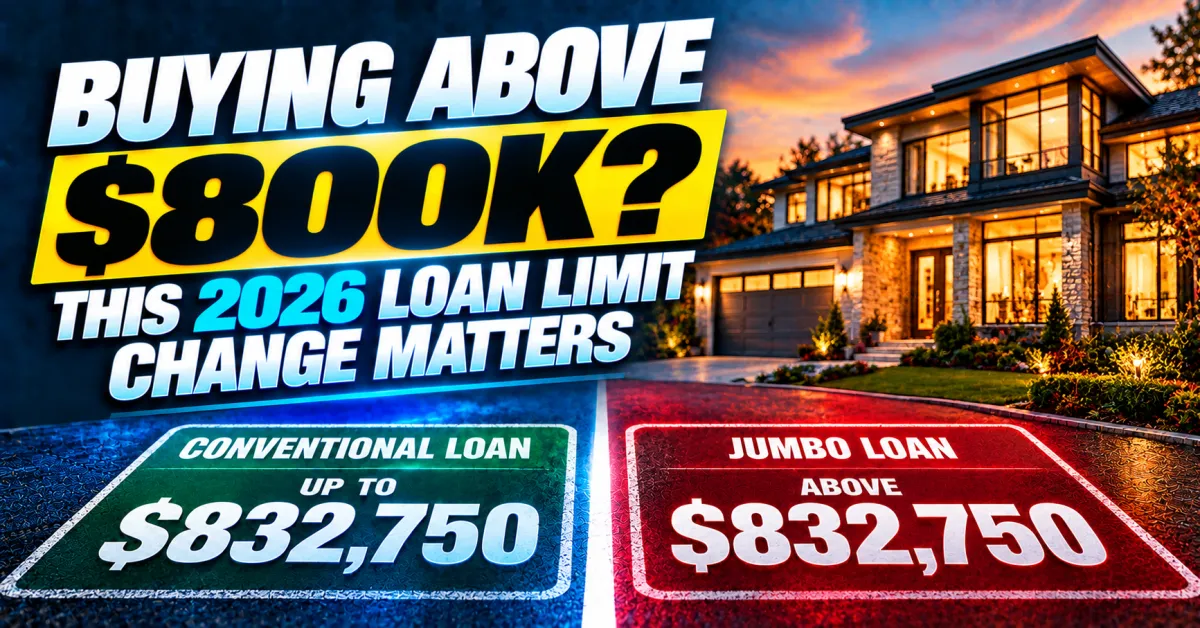
Buying Above $800K in 2026 and Why the New Conforming Loan Limit Changes Your Options Right Now
The Annual Adjustment That Opens New Doors for a Specific Group of Buyers
Every year the conforming loan limit is adjusted to reflect changes in home values nationally. For 2026 the baseline limit for a single-family home is $832,750. If you have been shopping anywhere in the $800,000 to $1,000,000 range Matt Brady wants you to understand what that number means for your financing before you make any assumptions about what kind of loan your purchase will require.
The Line Between Conventional and Jumbo and Why It Matters
The conforming loan limit is the dividing line between two fundamentally different lending environments and the two sides of that line operate very differently from each other.
Finance at or below the limit and you are in the conventional market. A larger pool of lenders participates in conventional lending which creates competition that generally produces better pricing and more flexible terms for the borrower. Underwriting guidelines are more standardized and tend to offer more flexibility across different borrower profiles. The range of available programs is significantly broader than what jumbo borrowers access.
Cross above the limit into jumbo territory and the dynamics change. Reserve requirements increase and lenders typically want to see more liquid assets remaining after closing. Credit score thresholds and debt-to-income standards can be stricter depending on the lender. Fewer lenders participate which reduces competitive pressure on pricing. The program options available narrow considerably compared to the conventional landscape.
For buyers who have the choice between staying conventional and crossing into jumbo the conventional side is generally the more favorable financing environment. The 2026 limit adjustment may give some buyers that choice for the first time.
Who Gains the Most From This Year's Adjustment
The buyers who benefit most directly are the ones who were sitting just above where last year's limit landed. Under the previous limit their required loan amount fell into jumbo territory. Under the 2026 limit that same loan amount may now qualify as conventional.
The practical outcomes of that shift are meaningful in both directions. A buyer who previously had no option but jumbo underwriting may now qualify under more flexible conventional guidelines. A buyer who was putting extra money down specifically to keep the loan amount below the old conforming limit may now be able to reduce that down payment and still stay in conventional territory, preserving cash for reserves, closing costs, or other financial priorities.
Why Your County Number May Be Higher Than the Baseline
The $832,750 figure is the national baseline for standard-cost counties. High-cost areas carry conforming loan limits that sit meaningfully above the national baseline because local home prices are substantially higher than national averages. In those counties the line between conventional and jumbo financing is higher than most buyers assume and the options available may be better than the national headline number suggests.
Message Matt Brady with your county and he will tell you exactly where the conforming limit falls in your specific market and how the 2026 adjustment changes what is available for your purchase.
Sources
FannieMae.com
FreddieMac.com
ConsumerFinancialProtectionBureau.gov
MortgageNewsDaily.com
Investopedia.com

Mortgage Calculator
See your total mortgage payments using the tool below.
| Year | Interest | Principal | Balance |
|---|
Social Media Links
YouTube
